

The Canadian government has introduced a significant tax reform during the Canada Investment Summit, enabling businesses to deduct investments in various sectors. This new initiative, known as the productivity mega-deduction, allows companies to write off the complete cost of new investments in areas such as machinery, equipment, clean energy, and zero-emission vehicles.
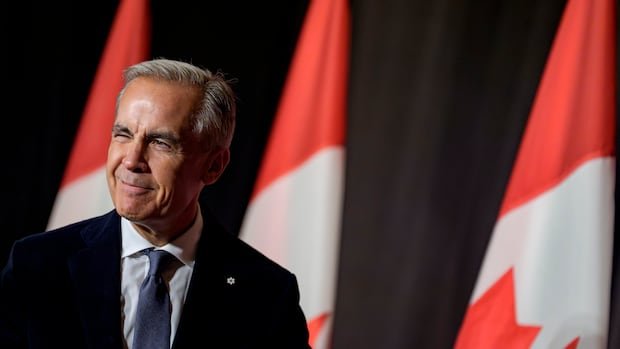
Prime Minister Mark Carney expressed the government’s aim to position Canada as the most appealing destination for investment among G7 nations. This reform expands on the productivity super-deduction introduced in the previous year’s budget, which initially covered a limited range of investments. With this expansion, approximately two-thirds of assets will now qualify for the deduction, compared to the initial 15 percent coverage.
Randall Bartlett, deputy chief economist at Desjardins, highlighted that Canadian companies previously recouped costs over project lifetimes, but the new program provides immediate refunds, potentially encouraging more substantial investments in new projects. This tax reform is designed to incentivize rapid and robust investment by companies, enhancing Canada’s competitiveness on the global tax landscape.
The government estimates that implementing this reform will cost around $36 billion over five years. Bartlett noted that current high oil prices are expected to offset the short-term financial impact, but long-term sustainability will require careful financial planning to ensure the government can support this level of spending.
Overall, this tax reform is seen as a crucial step to boost investment in Canada, particularly amidst economic uncertainties like trade wars. By offering these incentives, the government aims to retain businesses within the country and encourage them to pursue investments that were previously delayed due to uncertainty.